

MD&A · 2025
In this section4 topics
Overview of Operations
Overview of Operations
Executive Summary
Results Overview (Unit: Million THB) | Q4/ 2025 | Q4/ 2024 | YoY (%) | Q3/ 2025 | QoQ (%) | YE 2025 | YE 2024 | YoY (%) |
Operating Revenue | 2,938 | 2,659 | 10.5% | 2,627 | 11.8% | 10,738 | 10,062 | 6.7% |
Gross Profit | 1,054 | 1,139 | (7.5%) | 973 | 8.3% | 4,108 | 4,525 | (9.2%) |
Selling and Administrative Expenses (SG&A) | 829 | 827 | 0.2% | 885 | (6.3%) | 3,353 | 3,222 | 4.1% |
Net Profit for the Period | 169 | 244 | (30.7%) | 60 | 181.7% | 571 | 1,023 | (44.2%) |
Net Profit Attributable to the Equity Holders of the Company | 166 | 240 | (30.8%) | 59 | 181.4% | 562 | 1,008 | (44.2%) |
Gross Profit Margin (%) | 35.9% | 42.8% | - | 37.0% | - | 38.3% | 45.0% | - |
Net Profit Margin (%) | 5.7% | 9.1% | - | 2.3% | - | 5.3% | 10.1% | - |
Net Profit Margin Attributable to the Equity Holders of the Company (%) | 5.6% | 9.0% | - | 2.2% | - | 5.2% | 10.0% | - |
Basic Earnings Per Share (Baht/Share) | 0.55 | 0.80 | (31.3%) | 0.20 | 175.0% | 1.87 | 3.60 | (48.1%) |
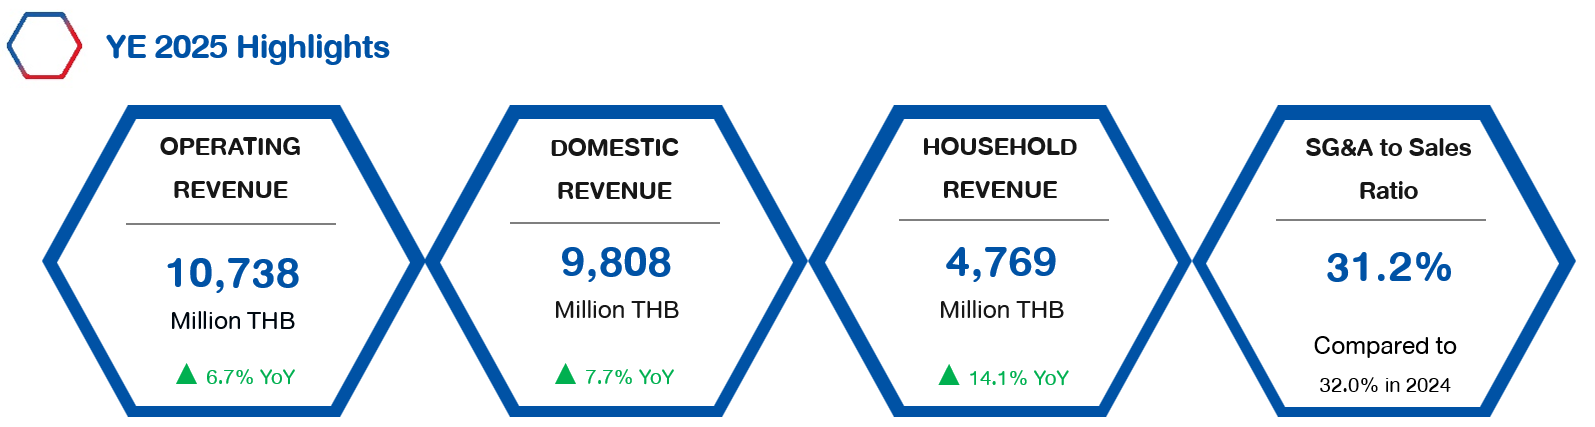
In Q4/2025, Neo Corporate Public Company Limited (the “Company” or “NEO”) reported total operating revenue of THB 2,938 million, increased by THB 279 million or 10.5% YoY, mainly driven by economic stimulus measures, including the increase in the State Welfare Card allowance and the “Half-Half Plus” co-payment scheme, which supported domestic consumer purchasing power. This reflects operating revenue of household and personal care segments grew by 18.6% and 17.5%YoY, respectively. Based on Nielsen (Thailand) data, the Company’s liquid detergent and fabric softener market values grew by 19.8% and 24.0%YoY, respectively, resulting in market share gains of approximately 176 bps (1.76%) and 200 bps (2.00%) to 29.2% and 13.0%, respectively. In addition, net profit attributable to the equity holders of the Company in Q4/2025 was 166 million, increasing significantly by 181.4% QoQ, primarily driven by growth in operating revenue, together with a reduction in selling and administrative expenses resulting from effective budget management, despite continued pressure from elevated cost of sales.
Operating Results & Financial Condition
Operating Results & Profitability
YOY: Q4/2025 Operating Revenue Structure and Analysis (Compared to Q4/2024)
Revenue Structure (Unit : Million Baht) |
Q4/2025 | % of Revenue |
Q4/2024 | % of Revenue | YoY (%) |
Operating Revenue – by Segment | 2,938 | 100% | 2,659 | 100% | 10.5% |
Household Products | 1,334 | 45% | 1,125 | 42% | 18.6% |
Personal Care Products | 824 | 28% | 701 | 27% | 17.5% |
Baby & Kids Products | 780 | 27% | 833 | 31% | (6.4%) |
Operating Revenue - by Geography | 2,938 | 100% | 2,659 | 100% | 10.5% |
Domestic | 2,717 | 92% | 2,407 | 91% | 12.9% |
International | 221 | 8% | 252 | 9% | (12.3%) |
Operating Revenue of the Company in 4Q/2025 was THB 2,938 million, increased by THB 279 million, or 10.5% YoY, due to the following factors:
Revenue from Household Products was THB 1,334 million, increasing significantly THB 209 million, or 18.6% YoY. The increase in revenue was primarily driven by the growth of the Fineline and Tomi brands, as well as the launch of the pet household category under the LovliTails brand in May 2025. The growth of Fineline brand was mainly from liquid detergent and fabric softener products. This was a result of the successful execution of strategies aimed at continuously increasing domestic market share, including the development of new products alongside the enhancement of existing ones (NPD & Relaunches). Revenue growth was partly driven by Fineline Concentrated Fabric Softener Deluxe Perfume, which features a premium fragrance offering long-lasting freshness, enhanced softness, and easier ironing. The product is available in a wide range of packaging sizes, from 20 mL sachets to 1,000 mL pouch, to cater to consumer needs across all segments. This product was launched as an NPD in Q3/2025 and has continued to generate steady sales momentum throughout the quarter.
Revenue from Personal Care Products was THB 824 million, increased by THB 123 million, or 17.5% YoY. The increase in revenue was driven by the growth of the BeNice, Eversense and Vivite brands, as well as the launch of the pet care category under the LovliTails brand in May 2025. The BeNice brand outperformed other brands, driven by a significant increase in revenue from liquid soap and moisturizing products. This was mainly from (NPD & Relaunches), including BeNice Happy Summer, which features a cooling sensation that delivers a clean and refreshing feel while boosting skin collagen with baby collagen, as well as the growth of BeNice Perfume Collagen Body Serum, a long-standing favorite among consumers. In addition, revenue growth was supported by the development of new products under the D-nee brand in the young adult body wash and moisturizing products, including the D-nee Blooming Glow Shower Cream series and D-nee Body Serum. These products have been promoted by a highly popular brand presenter, helping to enhance brand and product awareness.
Revenue from Baby & Kids Products was THB 780 million, decreased by THB 53 million, or 6.4% YoY. The decline was mainly due to decreased sales of liquid detergent and bottle cleaner products, largely from a slowdown in sales across the CLMV countries, together with a decline in demand for baby products in Thailand amid the current economic conditions. However, this decline was partially offset by growth of D-nee Deluxe products, especially liquid soap, fabric softener and talcum. This reflects the success of the Company’s strategy to expand its customer base into new segments, or the Segment Creator approach.
Gross Profit of the Company in Q4/2025 was THB 1,054 million, decreased by THB 85 million or 7.5% YoY, due to the significant increase in raw material costs, along with changes in the product mix. The proportion of revenue from the household products group, which has a lower gross profit margin than other groups, was 45% in Q4/2025, compared to 42% in Q4/2024. In addition, the Company recognized a depreciation expense of approximately THB 38 million from the personal care product manufacturing building (including utilities) after the building was ready for use in March 2025. As a result, the Gross Profit Margin in Q4/2025 was 35.9%, down from 42.8% in Q4/2024.
Net Profit Attributable to the Equity Holders of the Company in Q4/2025 was THB 166 million, decreased by THB 74 million, or 30.8% YoY. The primary factor was a decline in gross profit. Although selling and administrative expenses being recognized at a similar level to the previous year, the ratio of selling and administrative expenses to operating revenue in Q4/2025 was 28.2%, down from 31.1% in Q4/2024. However, the decrease in SG&A-to-Sales ratio was at a lower rate than the decrease in gross profit margin. As a result, the Net Profit Margin Attributable to the Equity Holders of the Company in Q4/2025 was 5.6%, down from 9.0% in Q4/2024.
QoQ: Q4/2025 Operating Revenue Structure and Analysis (Compared to Q3/2025)
Revenue Structure (Unit : Million Baht) | Q4/2025 | % of Revenue | Q3/2025 | % of Revenue | QoQ (%) |
Operating Revenue – by Segment | 2,938 | 100% | 2,627 | 100% | 11.8% |
Household Products | 1,334 | 45% | 1,194 | 46% | 11.7% |
Personal Care Products | 824 | 28% | 745 | 28% | 10.6% |
Baby & Kids Products | 780 | 27% | 688 | 26% | 13.4% |
Operating Revenue - by Geography | 2,938 | 100% | 2,627 | 100% | 11.8% |
Domestic | 2,717 | 92% | 2,439 | 93% | 11.4% |
International | 221 | 8% | 188 | 7% | 17.6% |
Operating Revenue of the Company in Q4/2025 was THB 2,938 million, increased by THB 311 million, or 11.8% QoQ, due to the following factors:
Revenue from Household Products was THB 1,334 million, increased by THB 140 million or 11.7% QoQ. The primary driver was the growth of the Fineline brand, particularly in liquid detergent and fabric softener products, along with the growth of Tomi brand in floor cleaner products and LovliTails brands. This was the result of the successful implementation of the Company’s strategy to continuously increase domestic market share. Revenue growth also reflected new product development and the enhancement of existing products (NPD and Relaunch), supported by 360-degree marketing under the “SHINE THE HAPPINESS” campaign in collaboration with “BUS,” a T-pop boy band, as part of the Company’s marketing and promotional activities, which continued to drive the growth of the Fineline brand under the “Happiness” series.
Revenue from Personal Care Products was THB 824 million, increased by THB 79 million, or 10.6% QoQ. The growth was driven by the strong performance of the BeNice and TROS brands, particularly in liquid soap and moisturizing products under the BeNice brand, which received positive feedback from consumers. This was the result of the successful implementation of the Company’s strategy to continuously increase domestic market share. The revenue growth also reflects the development of new products alongside the enhancement of existing ones (NPD & Relaunch), such as the BeNice Cherry in Love and BeNice Cherry Je T'aime were developed in response to the emerging Cherry Trend, which has gained strong momentum in the fashion and beauty segments. The products emphasize a bright, playful character with a sweet-and-tangy appeal, while maintaining their distinctive functional benefits. They are enriched with a Fruit Booster, a concentrated fruit-extract serum that helps nourish the skin, leaving it smooth, firm, bouncy, and naturally radiant. In addition, revenue growth was supported by growth from the Vivite, D-nee, and LovliTails brands.
Revenue from Baby & Kids Products was THB 780 million, increased by THB 92 million, or 13.4% QoQ. The primary driver was the growth of key baby care products, particularly liquid detergents, moisturizing, and liquid soap, together with continued growth across both Modern Trade and Traditional Trade domestic sales channels. In addition, export sales through the Company’s key overseas markets, particularly Vietnam and Laos, rebounded from the previous quarter. This was due to certain purchase orders postpone from the Q3/2025 to avoid the impact of the appreciation of the Thai baht.
Gross Profit in Q4/2025 was THB 1,054 million, increased by THB 81 million, or 8.3% QoQ, due to the increase in operating revenue as well as changes in the product mix. The proportion of revenue from the baby & kids products segment, which has a higher gross margin than other segments, stood at 27% in Q4/2025, compared to 26% in Q3/2025. However, the proportion of operating revenue increase 11.8% but lower the proportion of cost of sales 14.0%. mainly due to higher raw material costs. As a result, the Gross Profit Margin in Q4/2025 was 35.9%, down from 37.0% in Q3/2025.
Net Profit Attributable to the Equity Holders of the Company in Q4/2025 was THB 166 million, increased by THB 107 million, or 181.4% QoQ. The primary factor was a significant increase in operating revenue. In addition, the Company recognized a decrease in selling and administrative expenses from the previous quarter. mainly due to a reduction in advertising and promotion expenses. This was the result of effective budget management and cost control in line with the Company’s annual operating plan. The ratio of selling and administrative expenses to operating revenue in Q4/2025 was 28.2%, down from 33.7% in Q3/2025, this decrease was at a higher rate than the decrease in gross profit margin. As a result, the Net Profit Margin Attributable to the Equity Holders of the Company in Q4/2025 was 5.6%, up from 2.2% in Q3/2025.
YoY: YE 2025 Operating Revenue Structure and Analysis (Compared to YE 2024)
Revenue Structure (Unit : Million Baht) |
YE 2025 | % of Revenue | YE 2024 | % of Revenue | YoY (%) |
Operating Income – by Segment | 10,738 | 100% | 10,062 | 100% | 6.7% |
Household Products | 4,769 | 44% | 4,179 | 42% | 14.1% |
Personal Care Products | 3,011 | 28% | 2,748 | 27% | 9.6% |
Baby & Kids Products | 2,958 | 28% | 3,135 | 31% | (5.6%) |
Operating Income - by Geography | 10,738 | 100% | 10,062 | 100% | 6.7% |
Domestic | 9,808 | 91% | 9,105 | 90% | 7.7% |
International | 930 | 9% | 957 | 10% | (2.8%) |
Operating Revenue of the Company in YE 2025 was THB 10,738 million, increased by THB 676 million or 6.7% YoY, due to the following factors:
• Revenue from Household Products was THB 4,769 million, increased by THB 590 million or 14.1% YoY. The increase in revenue was primarily driven by the growth of the Fineline and Tomi brands, as well as the launch of the pet household category under the LovliTails brand in May 2025. The growth of the Fineline brand was mainly from liquid detergent and fabric softener products. This was a result of the successful execution of strategies aimed at continuously increasing domestic market share. The revenue growth also reflects the development of new products alongside the enhancement of existing ones (NPD & Relaunch). Revenue growth was partly driven by Fineline Concentrated liquid detergent “3-in-1” series, which delivers deep cleaning, wrinkle reduction, long-lasting softness, and a gentle fragrance all in one product, and has gained strong popularity among consumers with limited time. In addition, Fineline Concentrated Fabric Softener Premium Soft features pet hair and dust reduction technology, catering to pet owners who treat their pets as family members, as well as consumers with sensitive skin.
• Revenue from Personal Care Products was THB 3,011 million, increased by THB 263 million, or 9.6% YoY. The increase in revenue was mainly driven by the growth of the BeNice brand, particularly its liquid soap and moisturizing products, supported by continuous execution of a market share expansion–focused strategy, which enabled the Company to further increase its market share. In addition, revenue growth was supported by the expansion of the Eversense and Vivite brands and the launch of the LovliTails brand with its LovliTails Natural & Mild shampoo for dogs and cats, as well as the development of liquid soap and moisturizing products for young adults under the D-nee brand, such as the D-nee Blooming Glow body wash series and D-nee Body Serum, which were introduced to consumers for the first time this year.
• Revenue from Baby & Kids Products was THB 2,958 million, decreased by THB 177 million, or 5.6% YoY. This was primarily driven by a slowdown in the baby product market amid current economic conditions, as well as the impact of the conflict between Thailand and Cambodia. However, this decline was partially offset by growth in Vietnam and in D-nee Deluxe products, including fabric softener, liquid soap, liquid detergent, talcum, and moisturizing products. This reflects the success of the Company’s strategy to expand its customer base into new segments, or the Segment Creator approach.
Gross Profit in YE 2025 was THB 4,108 million, decreased by THB 417 million or 9.2% YoY, due to an increase in the cost of sales that outpaced the growth in operating revenue, primarily driven by a significant rise in raw materials costs. In addition, the Company recognized a depreciation expense of approximately THB 96 million baht from the personal care product manufacturing building (including utilities) after the building was ready for use in March 2025. As a result, the Gross Profit Margin in 2025 was 38.3%, down from 45.0% in YE 2024.
Net Profit Attributable to the Equity Holders of the Company in YE 2025 was THB 562 million, decreased by THB 446 million, or 44.2% from YE 2024. The primary factor was a decline in gross profit. In addition, the Company recognized an increase in selling and administrative expenses from last year, mainly due to higher spending on promotional activities, such as product displays in prominent retail store areas, to attract consumer attention, enhance the Company’s competitiveness, and support new product launches. However, the ratio of selling and administrative expenses to operating revenue (SG&A-to-sales) for YE 2025 was 31.2% down from 32.0% in YE 2024, while the gross profit margin declined significantly. As a result, the Net Profit Margin Attributable to the Equity Holders of the Company was 5.2% in YE 2025, down from 10.0% in YE 2024
Statement of Financial Position
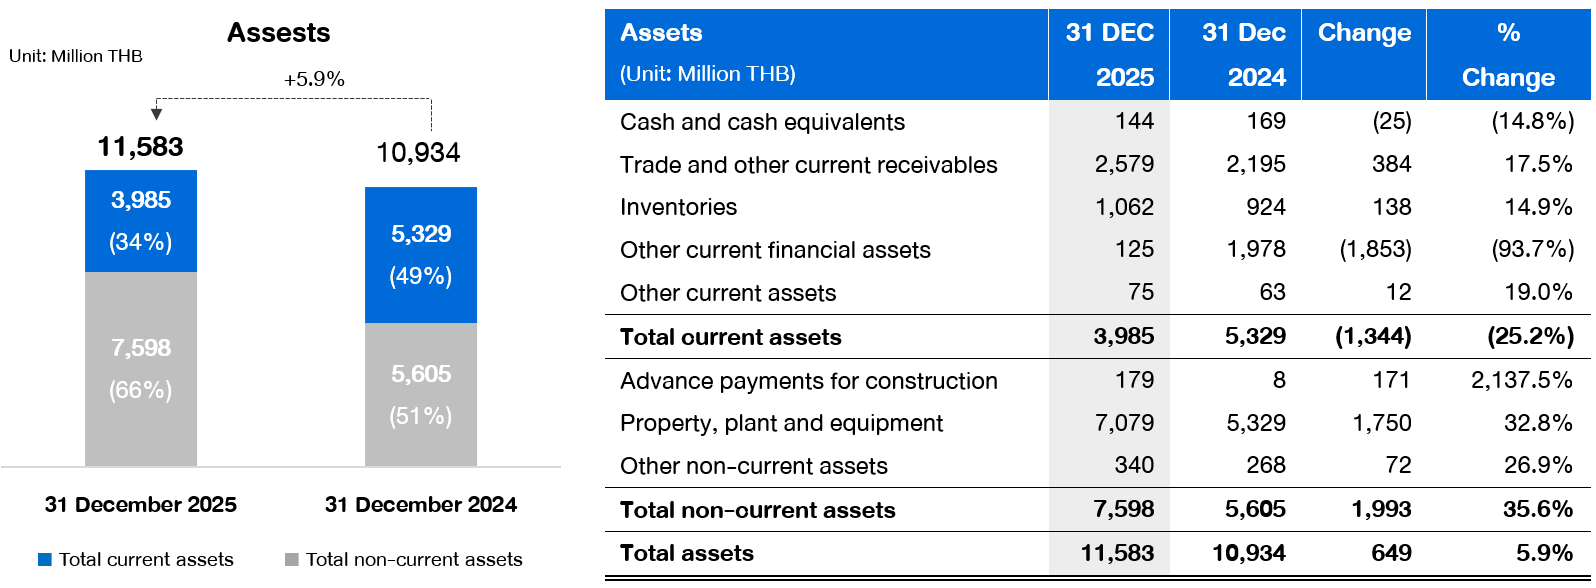
As of 31 December 2025, the Total assets of the Company were THB 11,583 million, increased by THB 649 million or 5.9% from 31 December 2024. The increase in total assets was mainly due to the increase in
(i) Property, plant and equipment of THB 1,750 million, mainly from construction investments to expand production capacity of the personal care and household plants (Phase 1)
(ii) Trade and other current receivables of THB 384 million, mainly from higher sales in November and December 2025 compared with the previous period, while the customer credit terms remained unchanged.
(iii) Advance payments for construction of THB 171 million, mainly from construction investments to expand the production capacity of the household plants (Phase 1)
(iv) Inventories of THB 138 million, mainly to support anticipated sales growth in the upcoming quarter.
However, the increase was partially offset by a decrease in
(v) Other current financial assets of THB 1,853 million, mainly from the withdrawal of fixed deposits to invest in construction projects to expand production capacity of the household plants (Phase 1).
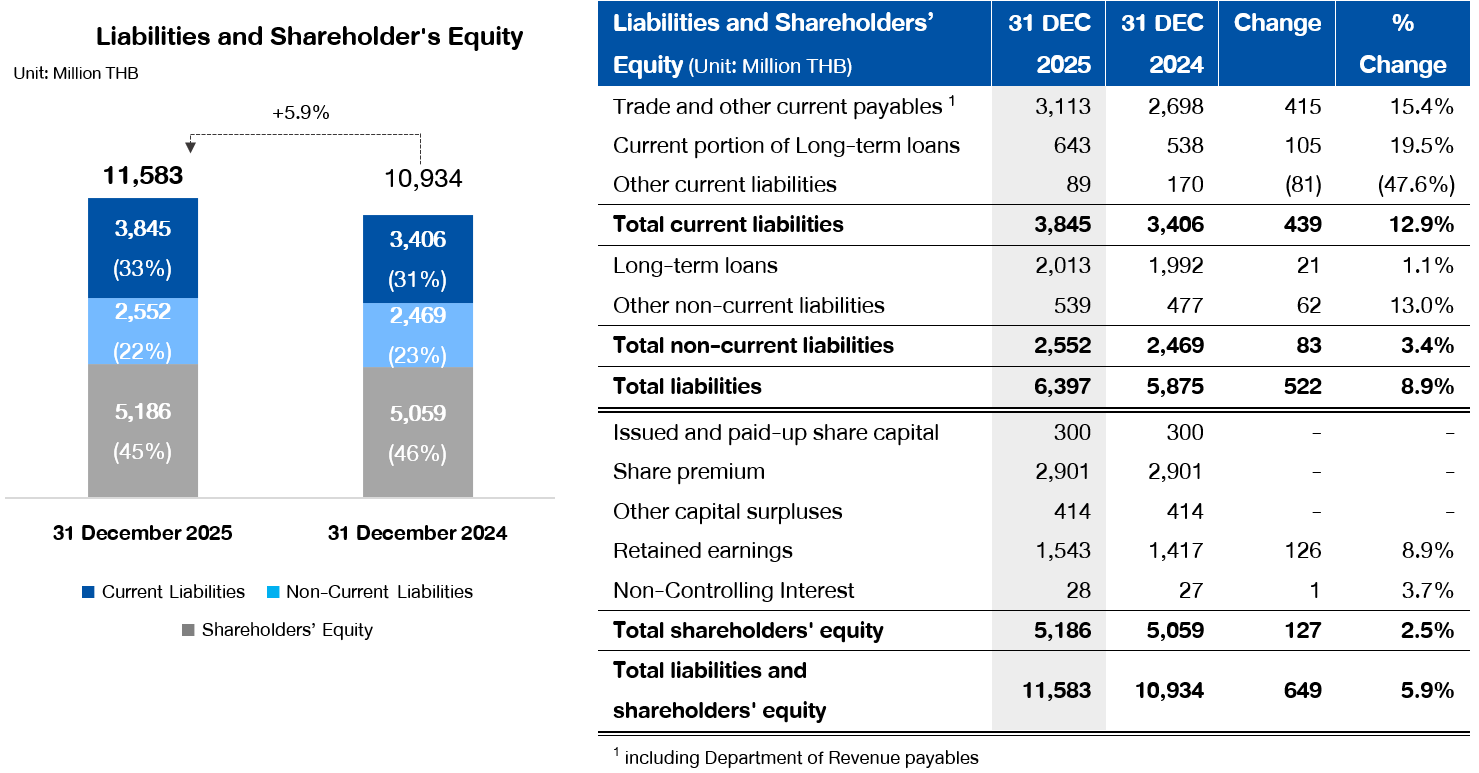
As of 31 December 2025, the Total liabilities of the Company were THB 6,397 million, increased by THB 522 million or 8.9% from 31 December 2024. The increase in total liabilities was mainly due to the increase in
(i) Trade and other current payables1 of THB 415 million, mainly from payables for construction and asset purchases for the household plant (Phase 1) expansion, along with raw materials and packaging to support increased production next quarter, as well as accrued expenses related to promotional activities
(ii) Net long-term loans from financial institutions (including the current portion of long-term loans) totaled THB 126 million, mainly from the final drawdown to fund the expansion project of the personal care production capacity.
However, the increase was partially offset by a decrease in
(iii) Accrued corporate income tax of THB 93 million.
Total shareholders' equity as of 31 December 2025 was THB 5,186 million, increased by THB 127 million from 31 December 2024. The increase was mainly due to higher retained earnings of THB 126 million, driven by total comprehensive income attributable to the Company’s shareholders of THB 531 million in YE 2025, partly offset by dividend payments of THB 405 million from the YE 2024 operating results.
Statement of cash flows for the year ended 31 December 2025
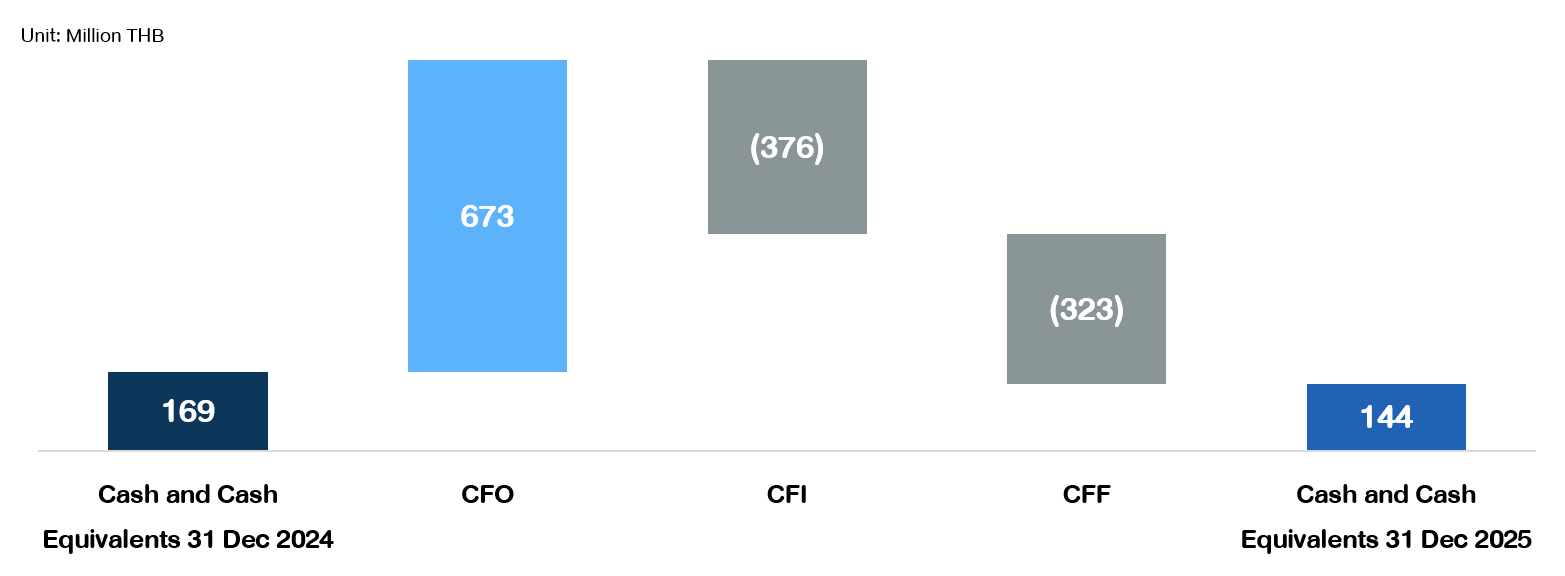
Net cash from operating activities of the Company for the period ending 31 December 2025 was THB 673 million, driven by the following key changes:
(i) Cash from operating activities of THB 1,011 million (mainly due to the record of pre-tax profit of THB 718 million and adjustments to pre-tax profit for cash receipts of THB 653 million, adjusted for a net increase in working capital of THB 360 million
(ii) Interest received of THB 19 million
(iii) Interest paid of THB 105 million, and
(iv) Corporate income tax paid amounted to THB 252 million.
Net cash used in investing activities of the Company for the period ending 31 December 2025 was THB 376 million, driven by the following key changes:
(i) Cash paid for the acquisition of plants and equipment of THB 1,981 million, mainly from construction investments to expand production capacity of the personal care and household plants (Phase 1), and
(ii) Cash paid in advance for construction of THB 244 million from construction investments to expand production capacity of the household plant (Phase 1), partially offset by
(iii) Net proceeds from investment in current financial assets of THB 1,871 million, mainly from the withdrawal of fixed deposits to invest in construction projects to expand production capacity of the household plant (Phase 1).
Net cash used in financing activities of the Company for the period ending 31 December 2025 was THB 322 million, driven by the following key changes:
(i) Cash repayment of long-term loans of THB 648 million, and
(ii) Dividend paid to the Company's shareholders of THB 405 million, partially offset by
(iii) Cash received from long-term loans amounted to THB 774 million, representing the final loan drawdown to fund the production capacity expansion project in the personal care product segment.
The Company’s Approach to Driving Business towards Sustainability (ESG)
The Company has developed a sustainable operations roadmap (ESG Activity Roadmap) to align with its circular economy policy and short-term and medium-term goals. The Company has plans and goals for promoting and developing sustainability, which aim to reduce environmental impact as follows:
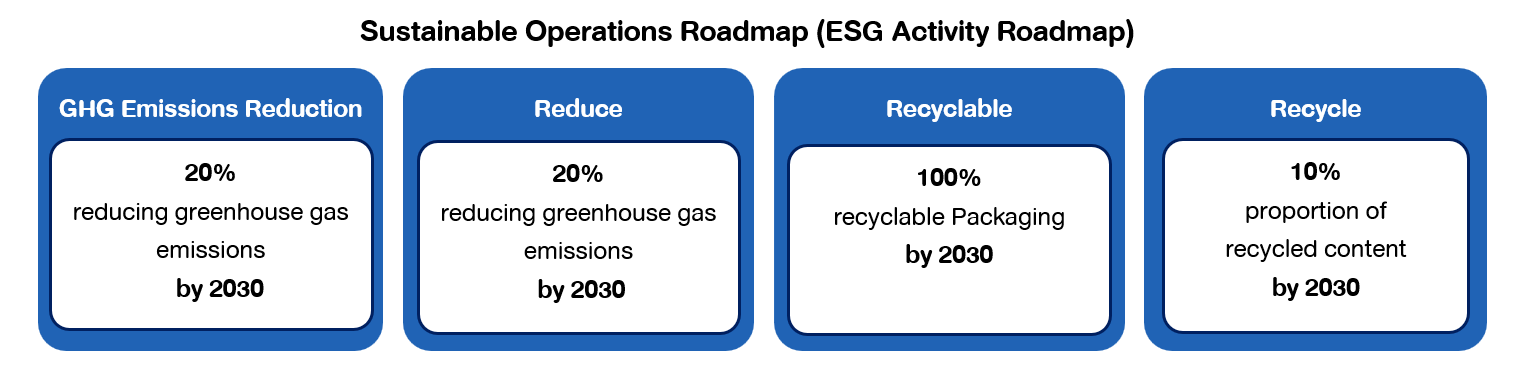
In 2025, the Company implemented its ESG Activity Roadmap, with details as follows:
GHG Emissions Reduction
The Company has assessed its organizational greenhouse gas emissions (Carbon Footprint for Organization: CFO) following the guidelines of the Thailand Greenhouse Gas Management Organization (Public Organization) and the international standard ISO 14064-1, which sets criteria for measuring and reporting greenhouse gas emissions since 2023. In addition, the Company remains committed to reducing greenhouse gas emissions through both short-term and long-term action plans. This includes collecting data on both emissions and carbon sequestration from all business. activities, covering all three scopes of greenhouse gas emissions.
In 2025, the Company transitioned from heavy fuel oil to liquefied natural gas (LNG), which helped reducing (CO2) emissions in Scope 1 by 16.0% and decrease air pollutants such as SO2, NOx, and PM, generating positive impacts on the environment and surrounding communities. Scope 2 greenhouse gas emissions showed an upward trend due to the construction of additional production facilities during the year, resulting in higher overall electricity consumption. However, the Company’s total organizational carbon footprint continued to decline compared with the previous year and remained 19.7% below the base year (2023), which is close to the Company’s short-term target of a 20% reduction from the base year. This reflects the Company’s continuous efforts in effective energy and fuel management, alongside collaboration with the supply chain to reduce carbon emissions across the value chain (Scope 3), the Company’s largest source of carbon. This reflects NEO’s strong commitment to Carbon Neutral and its path toward Net Zero through collaboration with business partners to deliver sustainable environmental outcomes.
Greenhouse Gas Emission Data of Neo Corporate Public Company Limited
Standard Criteria | Unit | Year 2024 | Year 2025 |
Scope 1 | tonCO 2 e | 4,877 | 4,098 |
Scope 2 | tonCO 2 e | 6,858 | 9,909 |
Scope 1 and 2 | tonCO 2 e | 11,735 | 14,007 |
Scope 3 | tonCO 2 e | 206,991 | 160,922 |
Note The 2025 data is a preliminary assessment based on the guidelines of the Greenhouse Gas Management Organization (Public Organization) and international standard ISO 14064-1. This data is currently undergoing verification and may be adjusted after the verification is completed.
Reduce (20% by 2025)
The Company reduced its use of virgin plastic by 1,851 tons, or 24% of its total plastic packaging usage volume, compared to the previous year, exceeding the short-term target set for the 2025 action plan.
Recyclable (100% by 2030)
The Company reported that recyclable packaging materials account for 82% of total packaging volume, while the remaining 18% consists of laminated film packaging, which is non-recyclable. The Company is developing a process to recover and reuse used laminated film, collaborating with the National Metal and Materials Technology Center (MTEC) and key laminated film manufacturers.
Recycled content (10% by 2030)
Beginning with 2023, the Company developed and tested plastic pellets produced from post-consumer plastic bottles, which were processed into post-consumer recycled (PCR) plastic pellets to support the circular economy. As of Q4/2025, packaging made from PCR plastic pellets had been utilized in a total volume of 296 tons, helping reduce greenhouse gas emissions by approximately 3,200 tons of carbon dioxide equivalent (CO2e), in alignment with the Company’s sustainability goals and its commitment to minimizing environmental impact.
Material & Related-Party Transactions
Related Party Transaction of the Company and/or its subsidiaries with persons who may have conflicts of interest for the fiscal years ended 31 December 2024 and 31 December 2025, are summarized as follows:
Lease Transactions
Description | Individual with potential conflicts of interest | Nature of transaction | Transaction value (THB million) | The Necessity and Reasonableness of the Transaction | Opinion of the Audit Committee. | |
2024 | 2025 | |||||
The Companyleases land for use as a parking facility. | Mr. Suthidej Thakolsri | Expenses | 0.75 | 1.12 | The Company leases land from Mr. Suttidet located in the vicinity of the Company’s head office, situated in Bang Chak Subdistrict, Phra Khanong District, Bangkok, for use as a parking area for employees and customers conducting business with the Company. The Company has entered into a total of 3 land lease agreements. Agreement No. 1 covers an area of 1,483.59 sq.m. at a rental rate of Baht 37,500 per month (approximately Baht 25.3 per sq.m. per month), with the contract ending on 28 February 2025. Agreement No. 2 covers an area of 2,058.01 sq.m. at a rental rate of Baht 54,600 per month (approximately Baht 26.5 per sq.m. per month), with the contract ending on 28 February 2025. Agreement No. 3 (renewal of Agreements No. 1 and 2) covers an area of 3,541.60 sq.m. at a rental rate of Baht 94,000 per month (approximately Baht 26.5 per sq.m. per month), with the contract ending on 28 February 2028, and the contract may be renewed for a period of 3 years each time. The rental rates and commercial terms are comparable to land leases in nearby areas with third parties. The Company expects that such transaction will continue in the future. | The land lease transaction arises from the necessity of the Company’s business operations and to facilitate employees and customers in conducting business with the Company. The Audit Committee has considered and is of the opinion that such transaction is reasonable and that the rental rate and commercial terms are comparable to those with third parties. |
Other Creditors | - | - | ||||
Debt Securities with Financial Ratio Requirements
Debt Securities with Financial Ratio Requirements Issued?
No
Factors That May Affect Financial Condition
Factors or Incidents That May Materially Affect Financial Condition
The Bank of Thailand expects Thailand’s economy to grow at approximately 1.5% in 2026, down from its 2025 forecast of 2.2%. The outlook is weighed down by domestic economic pressures, including elevated public debt levels, relatively limited growth in labor income, as well as temporary factors arising from delays in government budget disbursements. However, the Company’s operating performance in 2025 reflects its capability to generate sales growth exceeding both the overall domestic economic growth and the FMCG market in which the Company primarily operates, which expanded by approximately 4%. This was supported by the Company’s ability to promptly adjust its strategies in line with consumer needs, expand distribution coverage and channels in both domestic and overseas markets, and continuously expand into new consumer segments.
In 2026, the Company will further strengthen its strategy by offering more product options across different sizes and price points to meet the needs of all customer groups. The Company will also increase sales through social commerce and expand exports to highly potential countries to achieve its planned targets. In addition, the Company aims to grow its market share in Thailand in three key categories: liquid detergent, fabric softener, and liquid soap. The Company also plans to launch more than 200 SKUs, supported by expanded production capacity to accommodate the expected growth. These strategies are expected to drive mid-to-high single-digit average sales growth over 2023–2028 (5-year CAGR). However, the achievement of such growth will depend on various external factors, including economic and political conditions in Thailand and abroad, tourism levels, exchange rate fluctuations, and labor income growth, all of which may influence consumer purchasing power and, consequently, the Company’s future operating performance.
In 2026, the Company remains committed to the SustainNEOvation approach, with a continued focus on enhancing consumers’ quality of life through a diverse range of products developed under the principle of “responsibility.” This commitment begins with the careful selection of raw materials and the development of environmentally friendly formulations, which serve as a critical foundation for effective ESG management. As surfactants are the Company’s key raw materials, priority is given to biosurfactants derived from plant-based sources, particularly palm oil. These materials are readily biodegradable, environmentally friendly, and gentler on consumers’ skin more than other sources. However, as such inputs are derived from agricultural commodities (soft commodities), their prices are subject to volatility driven by external factors, including global demand, supply conditions, and weather patterns. Currently, raw material prices remain elevated, continuing from 2025, with no clear signs of a significant decline. The Company anticipates that sustained high raw material costs, together with higher depreciation expenses resulting from capacity expansion, may exert pressure on gross profit margin in 2026, keeping it at a level close to that of 2025. Nevertheless, actual performance will depend on prevailing market conditions and the overall business environment during the period.
To mitigate such uncertainties, the Company has prepared additional cost management measures for 2026, including adopting a spot-buy procurement strategy to diversify price risk exposure, enhancing product portfolio management to improve efficiency, and optimizing sales channel management. The Company will continue to closely monitor raw material cost trends and market conditions and adjust its strategies accordingly to align with evolving business conditions.